What if the driver who hit me has no insurance?
Reviewed by Andrew (Andy) R. Gillin
California State Bar #45226 ↗ · Approval recorded November 4, 2026
How we record review approvalYour own uninsured motorist coverage may help. This is coverage for some harm caused by a driver with no insurance. You must have the coverage and meet its rules.
In this guide
Here’s an example
A driver who has this coverage gets hit by an uninsured driver. They report the crash to their own insurer.
A made-up example to explain the idea. Your facts may lead to a different answer.How the rule works
This type of claim is often made to your own insurer. You still need to show that the other driver was at fault and that the policy applies. Coverage does not remove the need for proof.
Legal references: [1] Insurance Code § 11580.2 — Uninsured motorist coverage · [2] California Department of Insurance — Automobile insurance guide
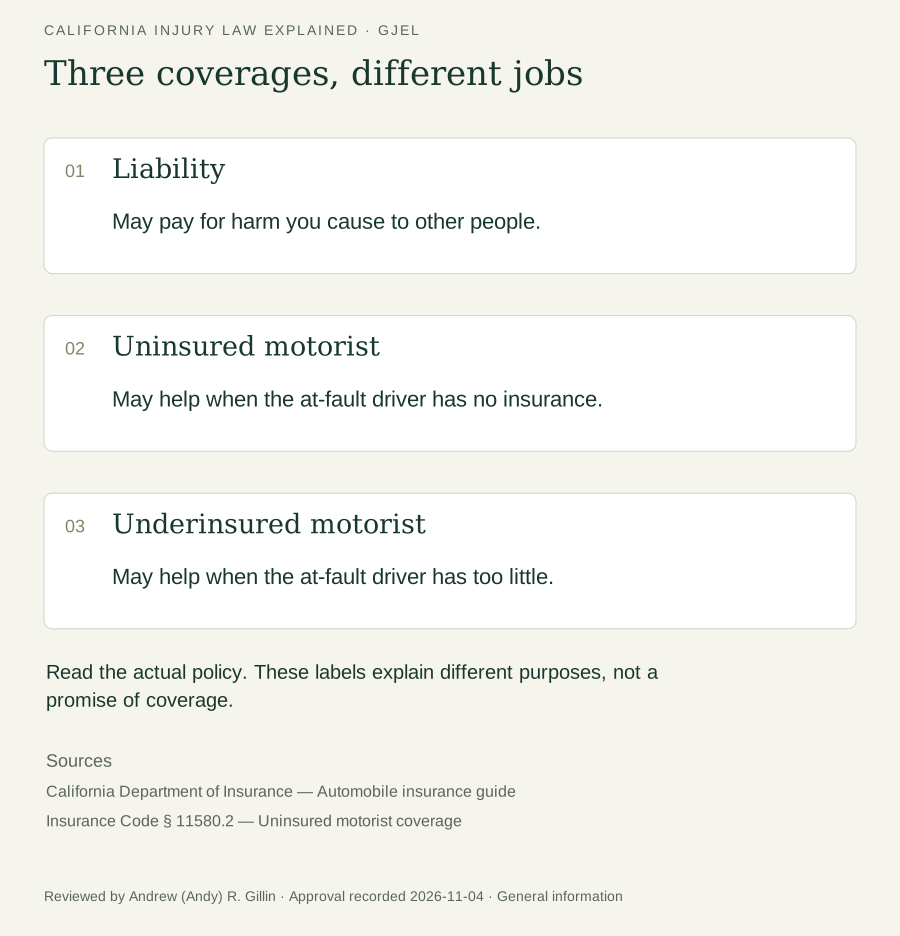
Three coverages, different jobs
Liability
May pay for harm you cause to other people.
Uninsured motorist
May help when the at-fault driver has no insurance.
Underinsured motorist
May help when the at-fault driver has too little.
Read the actual policy. These labels explain different purposes, not a promise of coverage.
Start with your own coverage
Look for uninsured motorist bodily injury coverage, often called UM. It is different from liability coverage. Liability usually pays for harm you cause to others. UM may help with harm caused by an uninsured driver.
Do not rely on the words “full coverage.” Read the coverage list and the policy. Check who is insured, which event is covered, the limits, and any steps needed to make a claim.
If you are unsure what your policy covers, read what liability-only coverage means.
Policy limits are a separate question. See California’s standard insurance minimums.
Coverage and fault are separate questions
Your own insurer may still ask for proof of fault, injury, and loss. Save photos, witness details, and care records. A policy does not turn every crash into an automatic payment.
A dispute about who is covered can differ from a dispute about fault or the amount of harm. Bouton explains that distinction. Ask which issue is in dispute before choosing the next step.
Keep the facts in one place with the evidence checklist.
When the driver cannot be found, check hit-and-run coverage rules.
What can change the answer?
Payment is not automatic. Notice, proof, policy limits, and time limits matter. Other parties may also share fault.
Questions people ask
Is uninsured motorist coverage required in California?
Insurers must offer the coverage under state law. A named insured can reject it in a signed writing that meets the law’s rules. Check the policy and any rejection form. Do not assume it was included.
Court decisions behind this answer
A case can help explain a rule. Its facts and limits matter too.
Bouton v. USAA Casualty Ins. Co.
Supreme Court of California · 2008
43 Cal.4th 1190, pp. 1193–1202
Some coverage questions belong in court. They differ from the fault and money issues a policy sends to arbitration.
This does not prove that a given person is covered. The policy, law, and kind of dispute matter.
Case applicability reviewed as recorded above.
A useful next step
Check your policy and coverage summary. Tell your insurer about the crash. Ask what steps are due and when.
If you are unsure which rule applies, a lawyer can review your facts and any deadlines. Learn about GJEL’s injury representation.
The law behind this guide
The references below support the legal discussion. Their application depends on the facts.
- Insurance Code § 11580.2 — Uninsured motorist coverage ↗Statute · Review recorded above
- California Department of Insurance — Automobile insurance guide ↗Agency guidance · Review recorded above
- Bouton v. USAA Casualty Ins. Co. (2008) 43 Cal.4th 1190 ↗Case law · Review recorded above
- Hartford Fire Ins. Co. v. Macri (1992) 4 Cal.4th 318 ↗Case law · Review recorded above
Updated 2026-11-04. Read our editorial standards.